
Nestlé Turns the GLP-1 Threat
Into a Product Strategy
The world's largest food company is using AI-assisted nutrition science to build a portfolio around weight-loss drug users — betting that appetite-suppressing medicines create a new market rather than simply erase an old one.
From Investor Anxiety to Product Roadmap
Nestlé is moving to turn the rapid rise of GLP-1 weight-loss medicines from a balance-sheet risk into a growth avenue. Chief Technology Officer Stefan Palzer told Reuters on August 17, 2026, that the company is using artificial intelligence alongside nutritional science to analyze clinical research, identify nutrient combinations, and design products specifically for people taking drugs such as Ozempic, Wegovy, Mounjaro, and Zepbound.
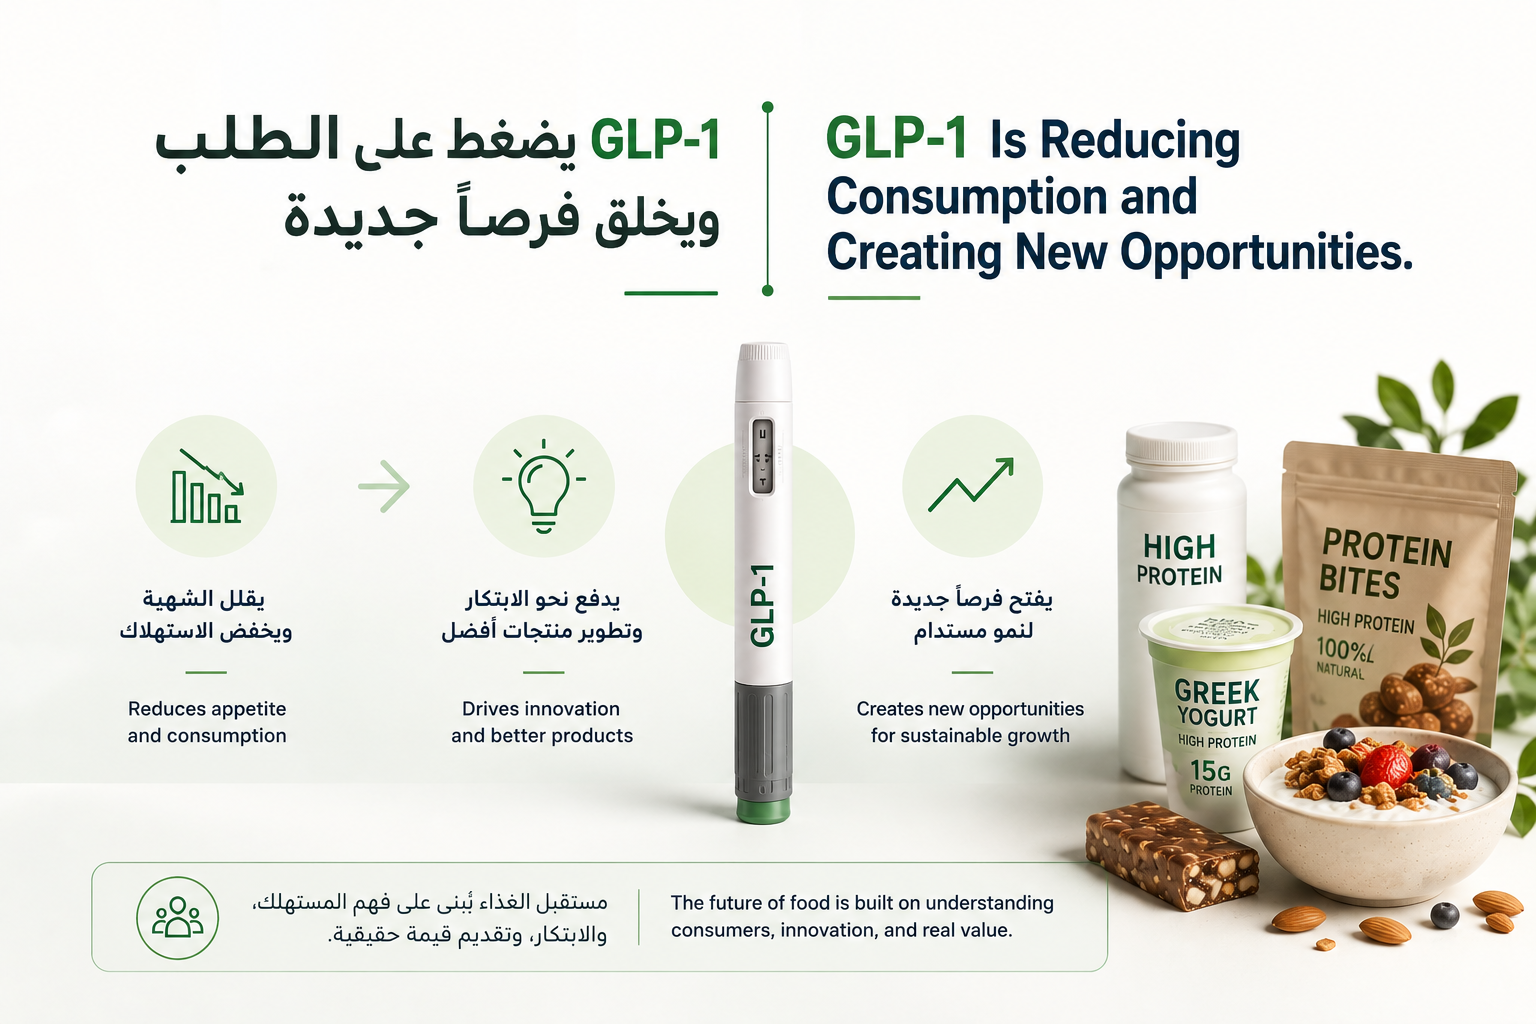
The strategic pivot responds to a concern that has weighed on packaged-food and beverage valuations since GLP-1 drugs from Novo Nordisk and Eli Lilly entered mass adoption: that appetite-suppressing medication could permanently shrink demand for snacks, packaged meals, and sugary beverages. Nestlé's counter-argument is that the same drugs are creating a distinct new category of need — nutritional support for people eating far less than before.
Key Takeaways
- Nestlé is using AI to process clinical research and identify nutrient combinations tailored to GLP-1 users, according to CTO Stefan Palzer.
- The company's research is centered on muscle preservation, hydration, and nutrient intake — the areas most affected by rapid, drug-induced weight loss.
- Existing products already reflect the strategy: the high-protein Boost Advanced Nutrition Shake in the US, collagen additions to Vital Proteins, and Milo PRO High Protein in Asia.
- Nestlé is reportedly avoiding the term "GLP-1" on packaging, instead building the connection to weight-loss drug users through social media messaging.
- An estimated 16 million Americans currently use GLP-1 medicines, according to Boston Consulting Group, with usage expected to keep climbing through the decade.
Designing for the Side Effects of Rapid Weight Loss
According to Palzer, Nestlé's scientists have been studying the physiological consequences of rapid weight loss rather than focusing only on appetite reduction. A central concern is lean muscle loss — a well-documented side effect of GLP-1 therapy that can accompany fat loss when calorie intake drops sharply. The company says it has identified a combination of two micronutrients, not yet publicly named, that it believes could support muscle recovery in this population.
The research extends to hydration and broader nutrient intake, both of which can be compromised when patients eat significantly smaller meals. Nestlé has also linked its expanded use of collagen protein in the Vital Proteins brand to concerns around skin, hair, and nail health, as well as facial volume loss — effects increasingly discussed among long-term GLP-1 users.
"-We are well positioned with the portfolio. It's a huge opportunity for our company."
A Portfolio Already Taking Shape
Nestlé's GLP-1 strategy is not starting from zero. The company's US business has already launched the Boost Advanced Nutrition Shake, marketed around 35 grams of protein to support muscle health during weight loss. In Asia, Nestlé introduced Milo PRO High Protein for the same purpose. Earlier moves in this direction include Vital Pursuit, a frozen-food line launched in 2024 as one of the first branded responses by a major food company to GLP-1 adoption, offering high-protein, fiber-rich, portion-aligned meals priced at $4.99 or below.
Notably, reporting indicates Nestlé is deliberately keeping the term "GLP-1" off its packaging, choosing instead to build the connection with weight-loss drug users through social media and targeted marketing. This reflects a broader industry sensitivity: framing products explicitly around medication use carries regulatory and reputational considerations that most food companies are still navigating carefully.
Why the Market Opportunity Is Real — and Still Early
The scale of the underlying market explains the urgency. Boston Consulting Group estimates that around 16 million Americans currently take GLP-1 medicines, a figure expected to rise sharply before the end of the decade. Globally, however, penetration remains modest: by some industry estimates, GLP-1 drugs currently reach roughly 7% of diagnosed diabetes patients and about 2% of the world's obese population — meaning the addressable market for companion nutrition products is still in its early stages of formation, not close to saturation.
That is precisely the opportunity Nestlé is pursuing: positioning itself early, before a nutrition-support category around weight-loss medication fully consolidates. The approval of oral GLP-1 formulations — the FDA cleared an oral version of Wegovy in December 2025 — is expected to widen the eligible user base further by removing the barrier of injectable administration, adding urgency to food companies' efforts to define this category before competitors do.
MENA Relevance: A Smaller, Faster-Growing Market
For Saudi Arabia and the Gulf, GLP-1 adoption is following the same direction as in Western markets, at an earlier stage and smaller scale. Market research firms project the Saudi GLP-1 agonist drug market to grow at a compound annual rate of roughly 13% between 2025 and 2030, reaching an estimated $121 million by 2030 — a figure that, while modest relative to the global market of tens of billions of dollars, signals a clear growth trajectory tied to rising obesity rates and government-backed treatment access.
The Kingdom's National Strategy for Obesity Control, introduced in 2023, has supported wider clinical access to evidence-based obesity treatment, including GLP-1 therapies, even as high costs and limited insurance coverage continue to constrain broader uptake. A study from King Abdulaziz University found Saudi patients using GLP-1 medications lost an average of roughly 10 kilograms, aligning with international clinical results and reinforcing local physician confidence in the treatment class.
For MENA food and beverage manufacturers, Nestlé's move is an early signal rather than an immediate market disruption. Regional GLP-1 penetration remains far below US levels, and insurance-driven cost barriers will likely slow adoption relative to the pace Nestlé is responding to in North America. Even so, companies serving the Gulf's growing health-and-wellness and functional-nutrition segments — protein-fortified dairy, portion-controlled meals, and fortified snacking — have a window to study Nestlé's category-building approach before GLP-1-linked nutrition needs become a mainstream commercial consideration locally.
Editorial Analysis
Nestlé's positioning illustrates a broader principle now shaping food and consumer health strategy: a pharmaceutical disruption to eating behavior does not have to translate into lost volume for food companies — it can translate into a different kind of volume, sold at a different price point, to a more specific need. The company's emphasis on muscle preservation, hydration, and micronutrient gaps reframes the GLP-1 conversation away from "less food" and toward "different food," a distinction that matters for how investors should read packaged-food demand forecasts going forward.
For the MENA region specifically, the more important signal is not the size of today's local GLP-1 market, but the direction of travel: rising obesity treatment rates, active government health strategy, and a young, digitally engaged consumer base historically quick to adopt global wellness trends. Food companies operating in Saudi Arabia and the Gulf have a runway — not indefinite, but real — to build category expertise in weight-management-adjacent nutrition ahead of the curve Nestlé is already responding to elsewhere.